Your house got cheaper. So why can’t you afford it?
The Wall Street Journal recently published an intriguing opinion piece by Allysia Finley titled “Hurray for Higher Mortgage Rates.”
Her argument is deliberately counterintuitive: Higher mortgage rates aren’t necessarily bad news. They suppress demand, discourage investors, slow home-price appreciation and eventually allow wages to catch up with housing prices. In other words, today’s painful mortgage rates may ultimately make homes more affordable.
It’s an interesting argument. But I’m not buying it.
I’ve been investing in and developing real estate for nearly 40 years. Higher interest rates certainly suppress demand. I’ve watched it happen many times.
But there’s a problem with calling that affordability.
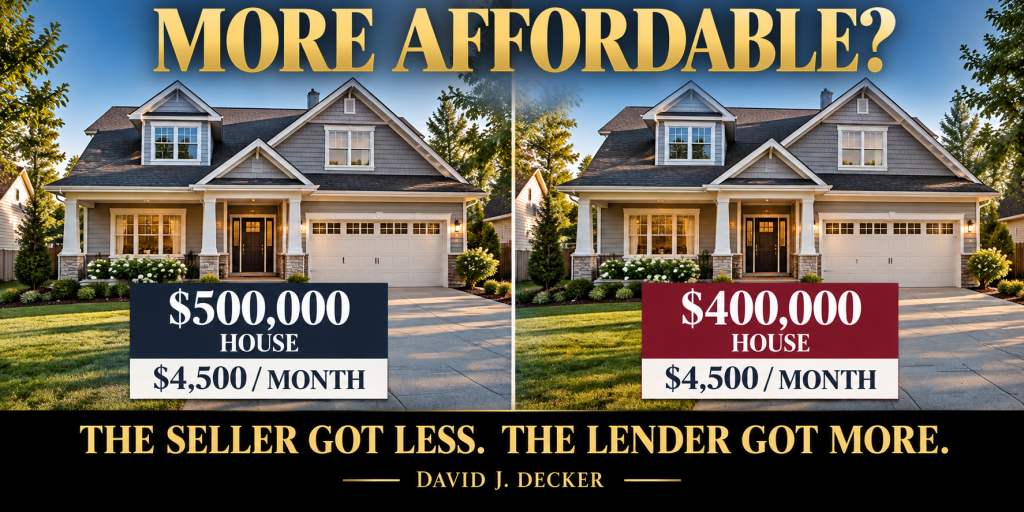
Suppose a house would sell for $500,000 when mortgage rates are low. Rates rise, buyers can no longer afford the payments, demand falls and eventually the seller accepts $400,000.
Success! We made the house $100,000 more affordable.
Except we didn’t.
What if the buyer’s monthly housing payment is still $4,500 because the interest rate is so much higher?
Is a $4,500 payment on a $400,000 house somehow more affordable than a $4,500 payment on a $500,000 house?
Not to the family writing the check every month.
Something else happened instead.
The seller got less money. The lender got more.
There are advantages to buying at the lower price. You need a smaller down payment. Your principal balance is lower. Property taxes may be lower. And if interest rates eventually decline, you may be able to refinance that $400,000 purchase and come out substantially ahead.
But rates may not decline. And the buyer has to afford the house today.
That’s the first problem with celebrating higher mortgage rates.
There’s another one that I understand particularly well as a developer.
Higher interest rates don’t just suppress demand for housing. They suppress the creation of housing.
Developers borrow money too.
When rates increase, construction loans become more expensive. Permanent financing becomes more expensive. The amount lenders will lend declines. Required returns increase. The value of a completed apartment project can decline.
Eventually a project that worked at one interest rate no longer works at another.
So it doesn’t get built.
That’s an awfully strange way to solve a housing shortage.
Higher rates also create another supply problem. Millions of Americans refinanced or purchased homes when mortgage rates were extraordinarily low. Someone sitting on a 3% mortgage has a powerful financial incentive not to sell that house and replace it with another one carrying a 7% mortgage.
The family stays put.
The house doesn’t come onto the market.
So yes, higher rates reduce demand.
But they can reduce supply at the same time.
I’m not arguing that artificially low interest rates are the answer. Cheap money creates distortions of its own. Give every buyer substantially greater borrowing power without creating another house and they’ll compete for the same limited inventory. Much of the benefit eventually gets capitalized into higher real-estate prices.
Nor do I think the answer is loosening underwriting standards so people can simply borrow more. Finley makes a good point there. Easier credit doesn’t necessarily make housing more affordable.
It may simply create another bidder with more borrowed money.
The more durable answer is considerably less exciting: Build more housing.
Make it easier to develop houses and apartments where people actually want to live. Reduce unnecessary regulatory costs and delays. Allow greater density where appropriate. Encourage construction rather than making the economics of construction increasingly difficult.
And then let incomes have a chance to catch up.
A lower home price is certainly desirable.
But let’s not confuse price with affordability.
A house isn’t affordable because the number on the purchase contract went down. It’s affordable when a household can reasonably handle the total cost of owning it.
If higher interest rates knock $100,000 off the price of a house but consume the savings in additional interest, we haven’t performed an affordability miracle.
We’ve mostly changed who gets the money.
Reality Face Punch: Making buyers unable to afford today’s home prices is a strange way to make housing more affordable.